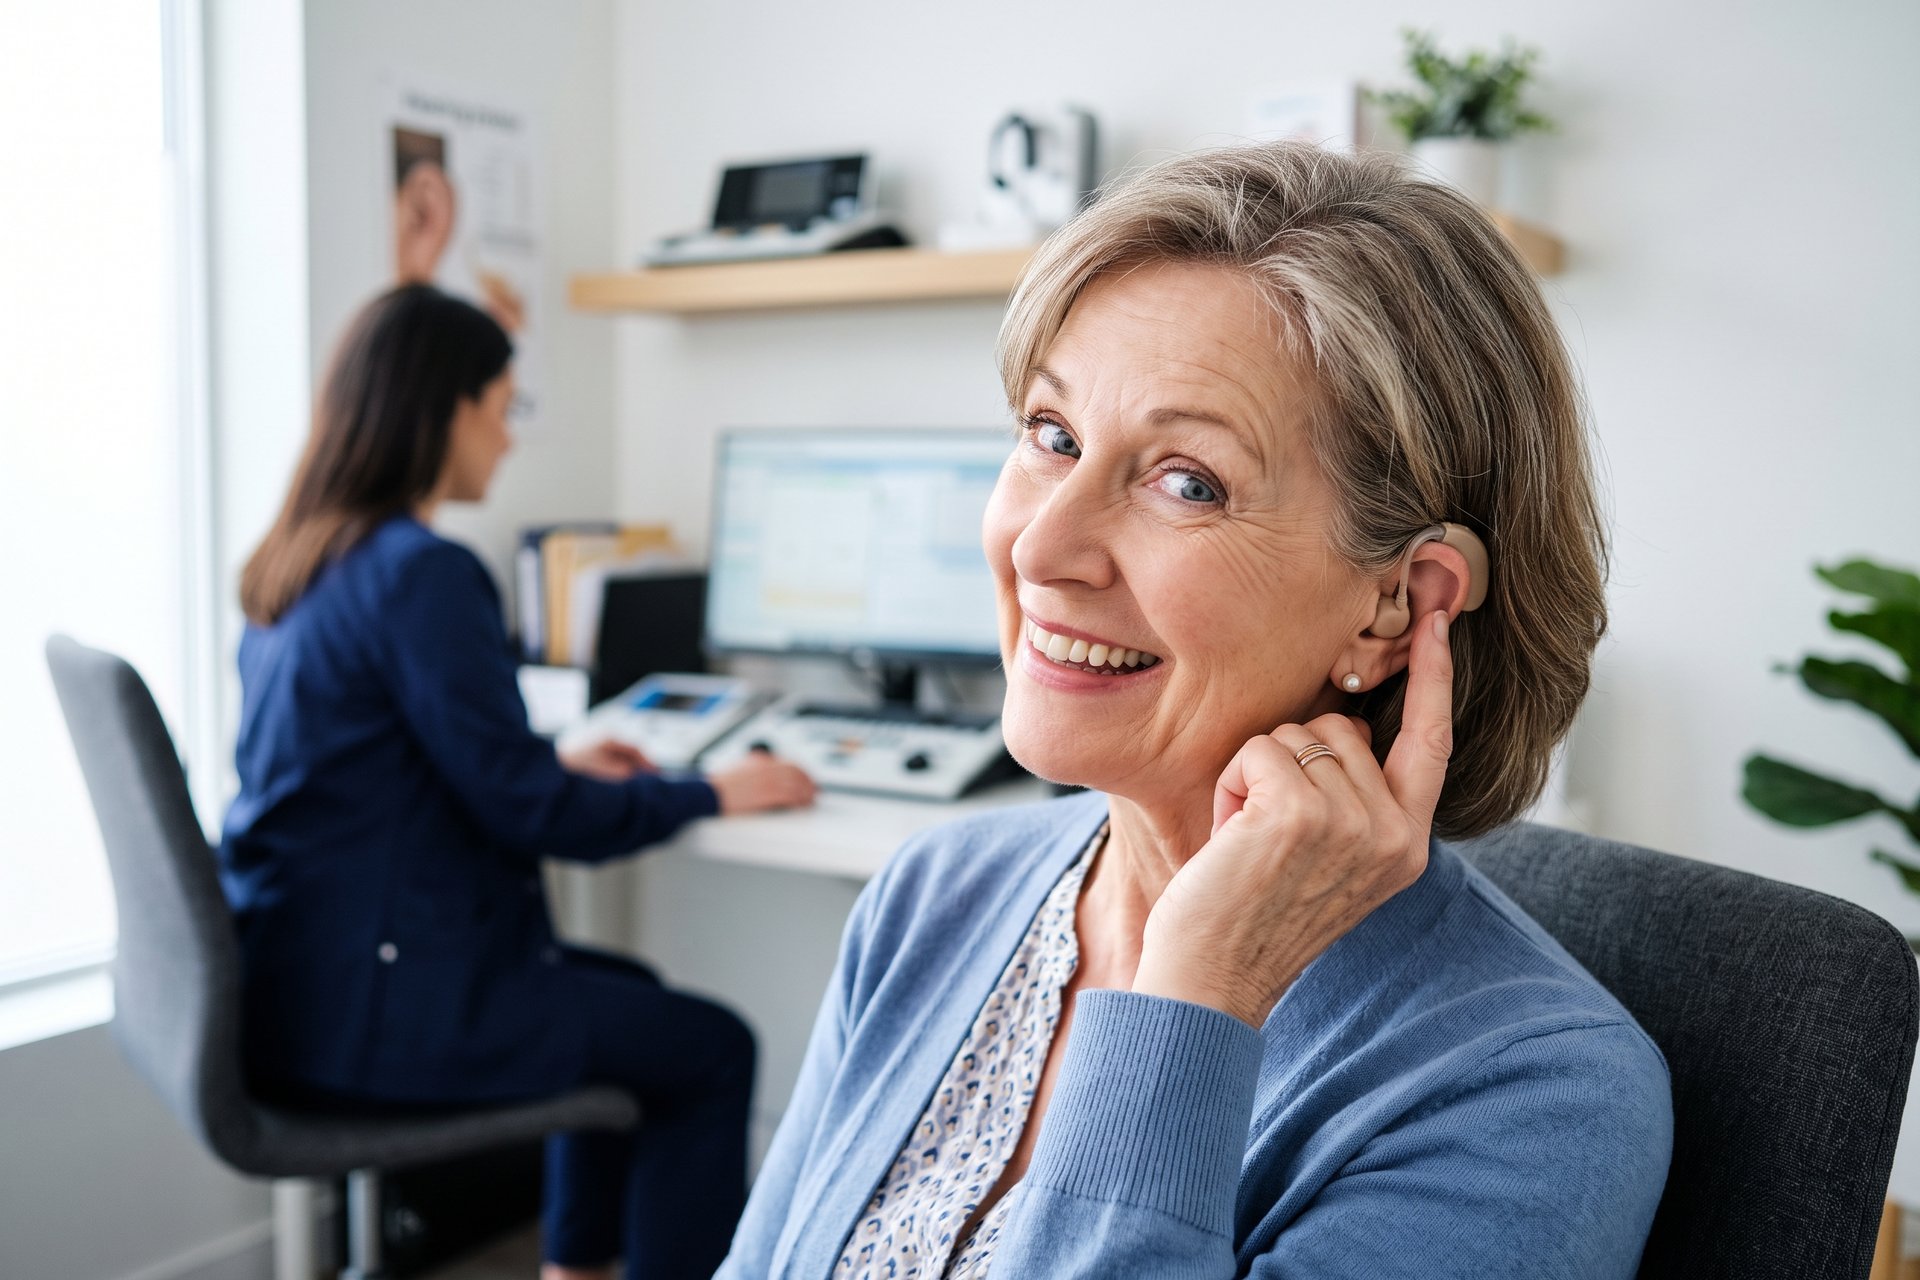
If you’ve put off buying hearing aids because of the price, Washington did you a favor.
Now that you can buy hearing aids over the counter, the average price is about $500, compared with $3,400 for a prescription device. That’s according to data cited in a JAMA Viewpoint article by two University of California, San Francisco (UCSF) professors, health economist Kathryn A. Phillips and physician Christine K. Cassel.
That’s $2,900 you get to keep — a new refrigerator or a lot of trips to the grocery store.
Buyers noticed. Of first-time hearing aid buyers, 70% went with an over-the-counter (OTC) device, the authors report.
Here’s the catch. One in five users of OTC hearing aids said they got no professional help at all. Only 51% got the full slate of help, which can include an evaluation, help choosing a device and a fitting.
And one study the authors cite found that only about a quarter of OTC hearing aid listings on Amazon could be verified as legitimate FDA-regulated hearing aids.
“Changing a regulation can create access,” Phillips said in a UCSF news release. Her point, which I agree with: Access doesn’t automatically come with a system that ordinary people can find their way through.
If you’re on Original Medicare, aka traditional Medicare, you’ll also pay every dime yourself. Original Medicare won’t pay for hearing aids or the exams to fit them.
In other words, the market opened the door and left buyers on their own. Here are six ways to make sure your $500 actually helps you hear.
1. Figure out whether OTC is meant for you
According to the Food and Drug Administration, OTC hearing aids are meant for adults 18 and older whose hearing loss seems mild to moderate to them. They’re not for severe or profound loss.
Notice who’s doing the judging: you. There’s no required exam, no prescription and no fitting by an audiologist.
The FDA lists red flags that mean you should see a doctor — ideally an ear, nose and throat specialist — before buying. Two examples: Your hearing changed suddenly within the last six months or you saw blood or fluid come out your ear in the past six months.
And if an OTC device doesn’t help enough, the FDA’s advice is to see a hearing professional.
You’re hardly alone in needing this. The National Institute on Deafness and Other Communication Disorders says 22% of people 65 to 74, and 55% of those 75 and up, have hearing loss that’s classified as disabling.
Yet among adults 70 and older who’d be helped by hearing aids, fewer than 1 in 3 have ever worn them, according to the institute.
2. Make sure it’s a hearing aid, not an amplifier
That Amazon finding should scare you. If only about a quarter of listings checked out, the odds of buying the wrong thing are real.
The FDA says the packaging on a genuine OTC hearing aid prominently shows two terms: “OTC” and “hearing aid.” If the box doesn’t say both, keep shopping.
Don’t be impressed by official-looking badges, either. The FDA warns that claims such as “FDA Registered” or “FDA Certified,” and an FDA logo on OTC hearing aid packaging, may be misleading.
Then there are personal sound amplification products, or PSAPs. The FDA says they’re meant to boost sound in certain situations for people whose hearing is normal. They’re regulated as consumer electronics, not medical devices, and the agency says they aren’t substitutes for hearing aids.
A cheap amplifier you didn’t need isn’t a bargain. It’s a waste.
3. Get one hearing test before you buy
Medicare may help pay for this one.
Medicare Part B covers diagnostic hearing exams when your doctor or another provider orders them to find out whether you need medical treatment.
You can also skip the doctor’s order and see an audiologist on your own, once in any 12-month span, but only in limited cases — including hearing conditions that aren’t acute.
Once you’ve met the Part B deductible, your share is 20% of what Medicare approves, plus a copayment if you’re seen in a hospital outpatient setting.
Remember, though: The test may be covered, but a fitting for hearing aids isn’t. You’re paying for the information, not the device.
I’d happily pay a modest share of an exam to know what I’m dealing with, rather than spend $500 on a hunch. Phillips and Cassel also suggest audiologists could offer one-off consultations to OTC buyers. It doesn’t hurt to ask whether one near you will.
Before you go — I write this newsletter the way I’d talk to a friend over coffee: honest, plain, and out to make you richer, not to sell you something. Sign up for the free Money Talks Newsletter. Free forever, and easy to quit if I ever bore you.
4. Ask for copies of your audiogram and device settings
Your audiogram is the chart of your hearing test results. If a professional programs a device for you, there’s also a record of those settings.
One of the authors’ proposals: Let patients take home their test results and the programming details for their devices, the same way you can walk out with your eyeglass prescription and shop anywhere.
That isn’t a guarantee yet. But nothing stops you from asking for both before you leave the office.
With your results in hand, you can shop around instead of being locked into one seller.
5. Read the return policy before you pay
The FDA requires the outside of an OTC hearing aid package to state the manufacturer’s return policy — or that there isn’t one. Read it before you pay.
Don’t count on a warranty. The agency’s OTC hearing aid rules don’t require manufacturers to provide one.
And don’t assume you’ll get a trial period. If the box says no returns, you’re making a $500 bet that a device you’ve never worn will work for your ears.
6. Pay with pretax money and check your Medicare Advantage plan
The IRS counts the cost of a hearing aid — plus batteries, upkeep and repairs to keep it working — as a medical expense.
That matters two ways. If you itemize, you can deduct the part of your medical and dental bills that exceeds 7.5% of your adjusted gross income.
And because health savings accounts use the same tax-law definition of medical care, hearing aids are generally eligible for HSA money. The devices are generally eligible for health flexible spending accounts too, depending on your plan.
Here’s what that’s worth. If the money would otherwise be taxed at 22%, paying for a $500 device with pretax dollars saves you $110 in federal income tax. Not bad for a few minutes of paperwork.
If you have Medicare Advantage, look at the extras. Some Medicare Advantage plans offer benefits Original Medicare doesn’t; contact the plan for details.
Do it before Medicare’s open enrollment period, which runs Oct. 15 to Dec. 7 each year, so you can switch plans for the next year.
Extras can change from year to year, as we laid out in “Your $0 Medicare Advantage Plan Just Got Worse. Check These 5 Things Before Dec. 7.”
If you’re comparing plans anyway, Medicare choices can change, so it pays to look closely.
The bottom line
Cheaper hearing aids are a genuine win. But a $500 device that’s wrong for you or that you can’t return, is just $500 gone.
Get tested, check the box, read the return policy and pay with pretax money. That’s how a lower price turns into better hearing.
Read the full article here