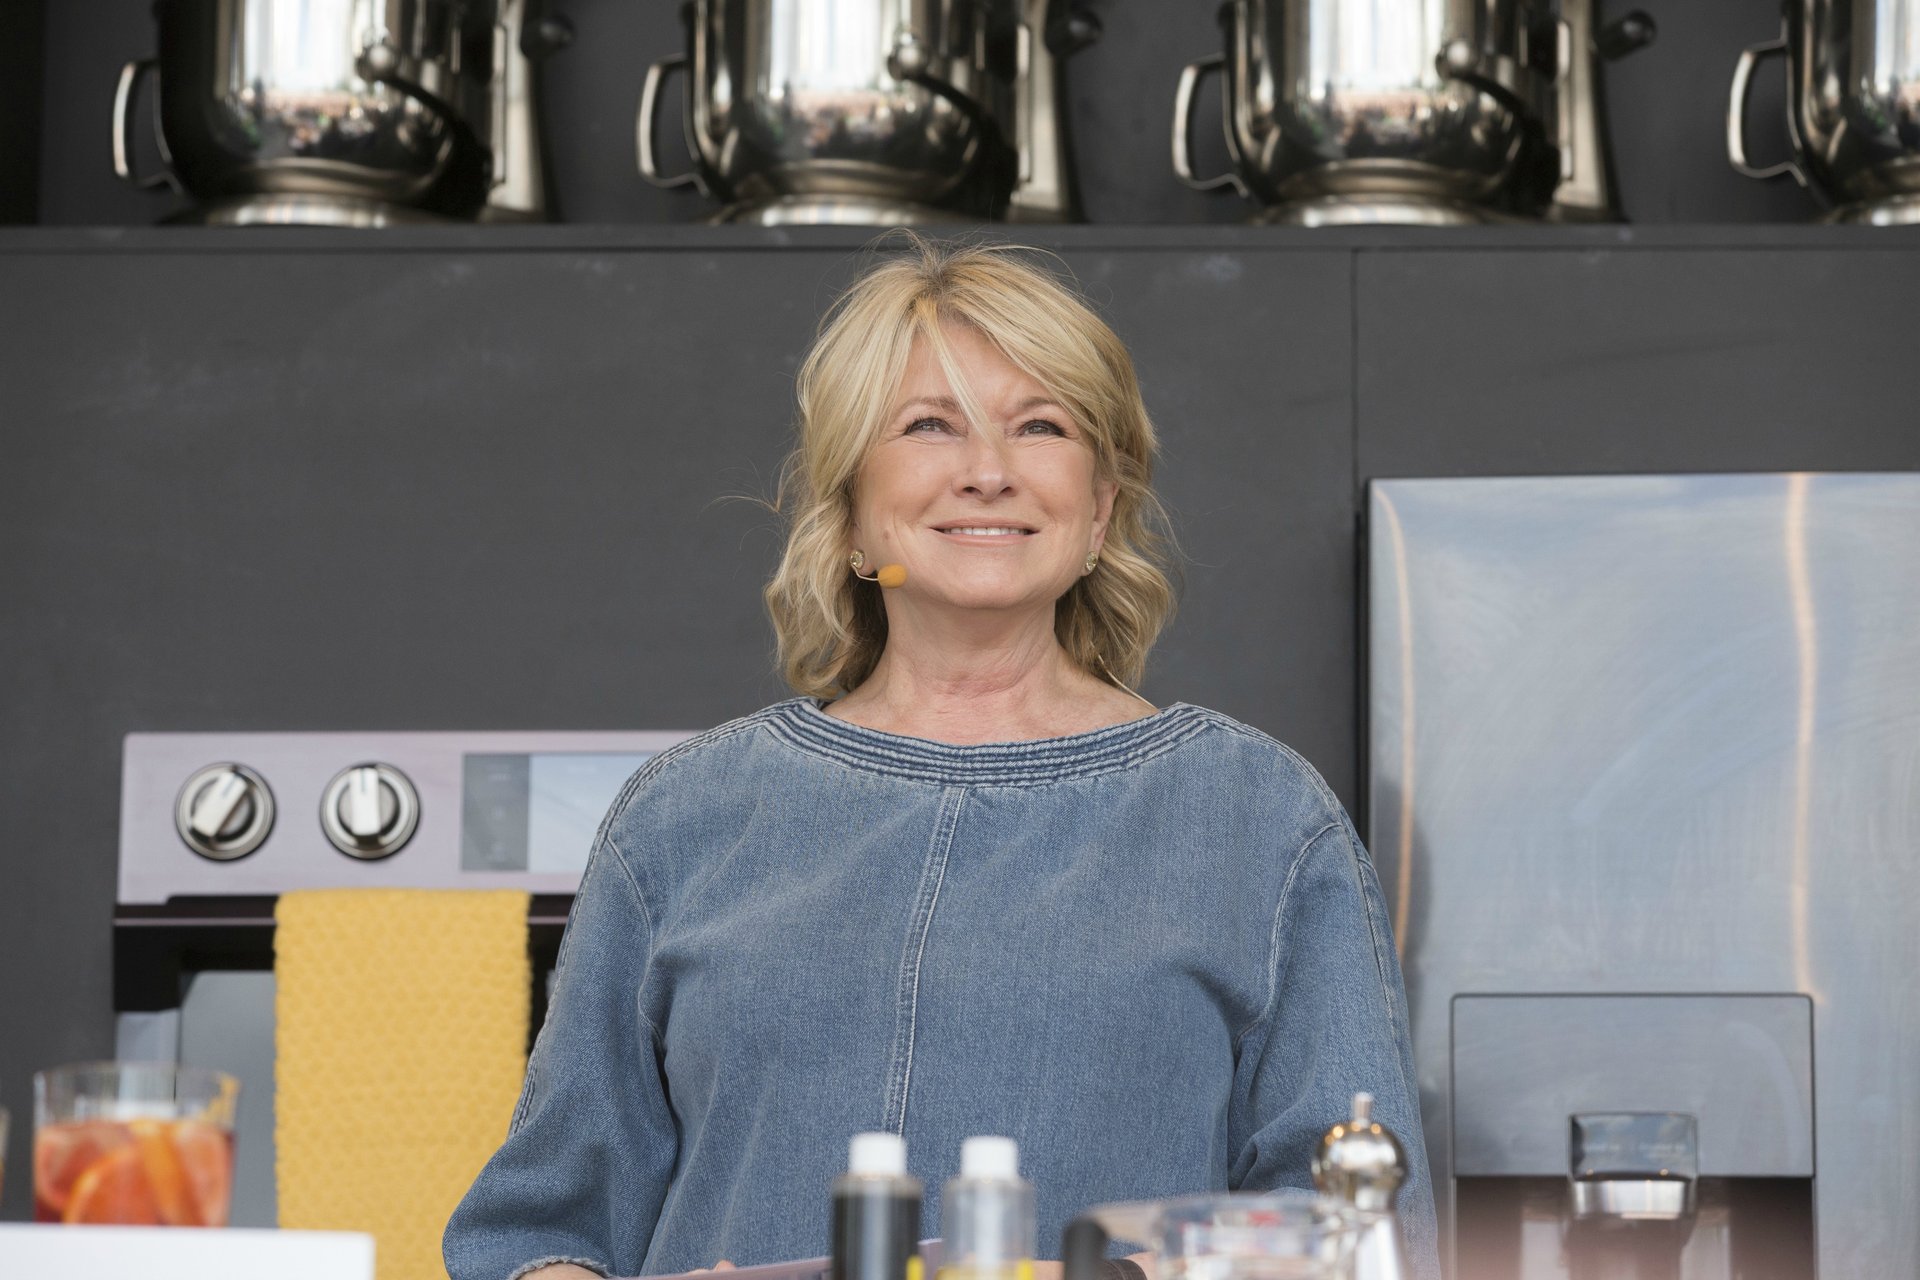
Martha Stewart is 85, and she has no patience for the idea that a career can be neatly weighed against the rest of life.
In an appearance on the “Richer Lives by SoFi” podcast with host Vivian Tu, Stewart said there’s no such thing as work-life balance, Hola! reported.
Plenty of Americans her age and younger are still clocking in. In 2025, 19.1% of people 65 and older were in the labor force, according to Bureau of Labor Statistics figures.
Workers 75 and older are the fastest-growing age group in the workforce, according to a Pew Research Center analysis.
A paycheck after 65 changes how several federal rules treat your money, from Medicare enrollment to retirement account withdrawals. Most of the changes work in your favor. One can raise a bill two years later.
1. Your employer’s size decides whether Medicare pays first
If you have health coverage through your or your spouse’s current job, the employer’s size matters. When the employer has 20 or more employees, the group plan pays first and Medicare pays second, according to the Centers for Medicare & Medicaid Services. If it has fewer than 20 employees, Medicare pays first.
That difference decides whether delaying Part B is safe. If your coverage is based on your or your spouse’s current job, you can generally wait, then use a special enrollment period that runs until eight months after the job or the job-based coverage ends, whichever comes first.
COBRA does not count as job-based coverage for this purpose. At an employer with fewer than 20 workers, though, Medicare pays first, so skipping Part B can leave you with gaps in coverage.
2. Medicare ends HSA contributions, sometimes retroactively
Workers with a high-deductible health plan often keep funding a health savings account (HSA) past 65. That stops once Medicare starts.
“Beginning with the first month you are enrolled in Medicare, your contribution limit is zero,” the IRS says.
The trap is timing. When you sign up for premium-free Part A after 65, Social Security can backdate your coverage up to six months, though never before your 65th birthday, Iowa’s state health insurance counseling program explains.
Contributions made during that window can be treated as excess contributions.
Applying for Social Security also enrolls you in Part A automatically, so Iowa’s program advises stopping HSA contributions six months before you enroll.
3. Waiting on Social Security still pays until 70
For anyone born in 1943 or later, each year you delay past full retirement age adds 8% to your benefit, and the increase stops at 70. A paycheck can make that wait easier to afford.
Once you reach full retirement age, the earnings test also drops away. Beginning that month, your earnings no longer reduce your benefits, no matter how much you earn, Social Security says.
Before that age, a paycheck can trigger temporary withholding, one of several rules that matter for anyone cutting back to part-time work before full retirement.
4. A paycheck can still raise your benefit
Your Social Security benefit is based on your highest-earning years. A strong year after you start collecting can replace a weaker one in that formula.
Social Security reviews every working beneficiary’s record each year. If the new earnings raise your monthly amount, the agency recalculates it and pays the increase retroactively to January of the year after the earnings. You do not need to file anything for the review to happen.
5. Your current 401(k) can wait on RMDs
Required minimum distributions, or RMDs, generally begin at 73, or 75 for anyone born in 1960 or later. Workers who are still on the job may be able to delay them from their current employer’s plan until the year they retire, as long as they do not own more than 5% of the business, the IRS says.
Check your plan’s rules to confirm it allows the delay.
The exception does not cover traditional IRAs, which must begin distributions at RMD age even if you are still working, or 401(k)s left behind at former employers. Those withdrawals follow the usual schedule, including the first-year deadline that can stack two withdrawals on one tax return.
6. You can keep funding an IRA at any age
The old age cap on traditional IRA contributions is gone. “For 2020 and later, there is no age limit on making regular contributions to traditional or Roth IRAs,” according to the IRS.
The requirement is taxable compensation, such as wages or self-employment income.
For 2026, savers 50 and older can contribute up to $8,600, including a $1,100 catch-up. A working spouse’s earnings can also support contributions for a spouse who is not working.
7. A big paycheck can raise your Medicare premiums later
Medicare premiums for higher earners are based on income from two years earlier. For 2026, Social Security generally uses 2024 tax returns, the agency says.
Individuals with a modified adjusted gross income above $109,000, or married couples filing jointly above $218,000, pay at least $81.20 more per month for Part B than the standard $202.90, plus at least $14.50 more per month for drug coverage.
That lag can sting in the first years after you stop working, when the bill reflects a salary you no longer earn.
Social Security lets you ask for a lower amount with Form SSA-44 after a life-changing event, including stopping work or cutting your hours. You will need documentation, such as a letter from your employer about your retirement.
These decisions overlap, and the dates rarely line up on their own.
If you have $100,000 or more in investments, SmartAsset’s free matching service can connect you with up to three fiduciary financial advisors who can help coordinate them. The questionnaire takes about 10 minutes and asks for a phone number near the end, and you control whether and when you respond to anyone.
No balance, but a calendar
Stewart may be right that work and life never balance out. The rules above reward something more modest: knowing the dates. The best time to sort them out is the year before you leave the job, while the paycheck, the employer health plan and the 401(k) are all still in play.
Read the full article here