
When a fire, an automobile accident or property damage upends your life, the emotional and practical toll can last weeks, months or even years. This is before the financial consequences are considered.
Being underinsured does not just mean you receive a smaller check. You carry the shortfall, and having no money doesn’t make it disappear. Sometimes it means you cannot replace what you lost. Sometimes it becomes a debt that follows you for years, potentially enforced through lawsuits, liens or garnished wages.
Home underinsurance
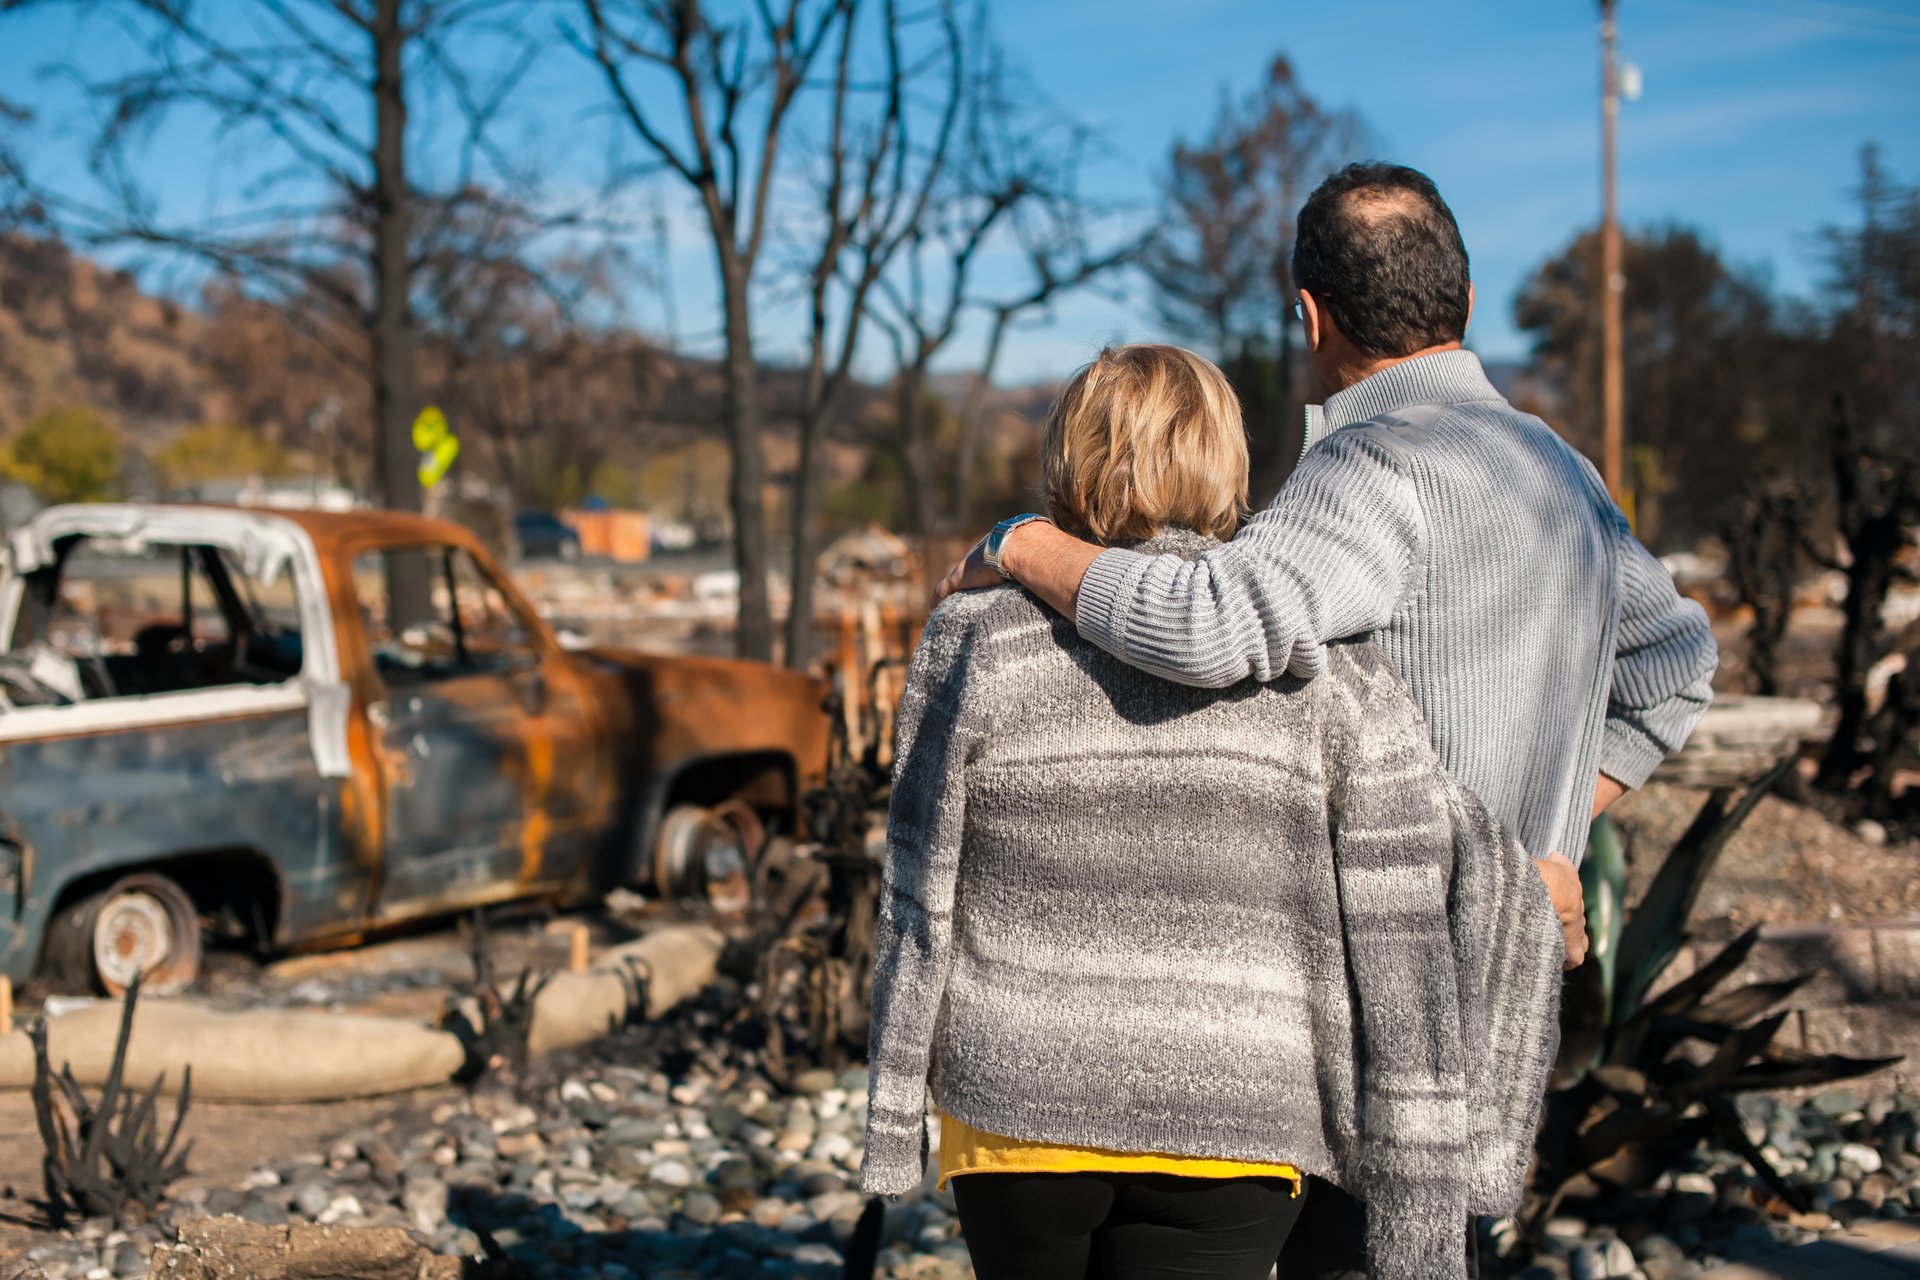
For homeowners, underinsurance often surfaces only after a major loss. United Policyholders, a nonprofit that has surveyed wildfire survivors since 2007, consistently finds about two-thirds come up short, typically by $200,000 or more. After the January 2025 Los Angeles fires, the group’s one-year survey found 69% of total-loss households did not have enough coverage to rebuild.
Rebuilding costs have climbed sharply since 2020, and policy limits have not always kept pace. If your house is insured for what it cost to rebuild a decade ago, you can be six figures short of rebuilding it today.
Your options are to rebuild smaller, rebuild in a lower-cost area or sell the lot. Staying may mean draining savings or borrowing, sometimes through a low-interest Small Business Administration disaster loan, which is open to eligible homeowners after a federally declared disaster.
For a household in its 60s, borrowing to rebuild a house that was already paid off can undo years of planning. One Altadena family renovated without raising their coverage and came up at least $100,000 short after the Eaton Fire.
Insurify lets you compare real-time home insurance quotes side by side without the spam. It’s fast, secure, and rated 4.7 stars on Trustpilot.
Renters underinsurance
A renters policy does two jobs. One covers your belongings. The other covers damage you cause to someone else’s property.
If your belongings are insured at actual cash value rather than replacement cost, depreciation comes out of the settlement, and you must make up the difference yourself.
Liability can be far more expensive. If you leave a stove unattended and start a fire, your landlord’s insurer pays to repair the building. It may then try to recover what it paid from you, a process called subrogation. A common renters liability limit is $100,000. If the bill runs past your limit, or you had no policy, the insurer can sue, win a judgment and collect through garnished wages or a levy on your bank account. Whether it can pursue you at all depends on your state and your lease.
Your landlord’s insurance rebuilds the walls. Everything inside is on you. Insurify renters insurance makes it easy to fix that.
Car underinsurance
If you total your own car, the insurer generally pays its actual cash value just before the crash, minus your deductible. That figure is meant to reflect the market value of a comparable used vehicle, but local prices, sales tax and fees can still leave you short of replacing it. If you owe more on the loan than the car is worth, you may also be left paying the difference unless you carry gap coverage.
Either way, you cover the shortfall, borrow more or settle for something cheaper.
Liability is a heavier risk. Your insurer pays up to your limit, and you pay for everything above it. Many state minimums are strikingly low. Florida requires just $10,000 in property damage liability. A crash with serious injuries can quickly push costs beyond your coverage. The injured party can sue for the difference and collect through garnished wages, liens or levies, and the judgment may follow you for years.
The same gap can hurt you when someone else is at fault. If a driver with insufficient coverage seriously injures you, their insurer stops paying at their limit. Underinsured motorist coverage on your own policy is designed to fill that gap, though what it covers varies by state.
Save up to $1,100 on your car insurance with Insurify.
Get the right coverage
Insurance costs may seem excessive and unnecessary until an unexpected disaster hits. Underinsurance is invisible until you need every dollar of the policy. Do not wait for a disaster to check. Consider what you would do if a pipe burst next month and your policy paid less than the repair. If covering the balance would mean borrowing or falling behind, that is a coverage gap worth examining now.
Check that your home is insured for today’s rebuilding costs, whether your belongings are covered at replacement cost or actual cash value, and how your auto insurer values a totaled car. Review the liability limits on your renters and auto policies, because those numbers can turn a bad day into debt. Raising a limit often costs far less than the gap it closes.
Insurance pays for the extraordinary expenses you cannot pay out of pocket. Take 10 minutes now to shave hundreds of dollars off your home, renters or car insurance.
Join over 10 million people who have taken back control and stopped overpaying. It costs you absolutely nothing to check.
Read the full article here